35,000+ smart investors are already getting financial news, market signals, and macro shifts in the economy that could impact their money next with our FREE weekly newsletter. Get ahead of what the crowd finds out too late. Click Here to Subscribe for FREE.
September has a habit of exposing expenses that were easy to ignore during summer. Vacations end, routines return, heating season approaches, annual renewals start appearing, and a handful of seemingly harmless monthly charges can suddenly look much less harmless.
For Canadian households trying to create more breathing room without making dramatic lifestyle cuts, the easiest savings may already be hiding in bank statements, utility bills, insurance policies and everyday driving habits. Some cost only a few dollars at a time, but repetition is what makes them expensive. These 22 small money leaks Canadians should fix before October range from forgotten digital subscriptions and banking charges to wasted food, unnecessary fuel consumption and investment fees that quietly reduce long-term returns.
A Streaming Stack That Grew Without Anyone Noticing
22 Small Money Leaks Canadians Should Fix Before October
- A Streaming Stack That Grew Without Anyone Noticing
- App and Cloud Subscriptions Hiding in the Background
- Retail Memberships That No Longer Earn Their Keep
- A Chequing Account That Still Charges Too Much
- ATM Withdrawals That Trigger Multiple Fees
- NSF Charges Caused by Poor Timing
- A Rewards Card Whose Annual Fee No Longer Makes Sense
- Credit-Card Interest on Purchases That Never Really Get Paid Off
- Buy-Now-Pay-Later Purchases That Have Started to Stack Up
- Credit-Card Balance Insurance That Duplicates Other Protection
- Mobile Data and Add-Ons That No Longer Match Actual Usage
- An Internet Promotion That Quietly Reverted to the Regular Price
- Groceries That Are Purchased but Never Eaten
- Electronics Drawing Power While Nobody Is Using Them
- A Thermostat Schedule Left in Summer Mode
- Drafts and Dirty Filters Making the Heating System Work Harder
- Underinflated Tires Burning More Fuel
- Idling That Turns Fuel Into Nothing
- Premium Gas in a Vehicle That Does Not Require It
- Auto Insurance Still Based on an Old Driving Routine
- Home Insurance Renewing Without a Proper Review
- Investment Fees That Seem Tiny Until They Compound
- 16 Costco Canada Habits That Could Be Costing Shoppers More Than They Save
Streaming was supposed to make entertainment simpler, yet many households gradually accumulate separate subscriptions for television, movies, sports, music and specialty programming. Statistics Canada reported that prices for video and audio subscription services in 2024 were 21% higher than in 2019 and 52.7% higher than in 2014. It also noted that consumers increasingly need more than one service to access the programming they want. That makes a forgotten $10 or $15 subscription more meaningful than it once seemed.
September is a useful month for a streaming audit because summer viewing habits may no longer reflect the household’s fall routine. Reviewing the last three months of credit-card and bank statements can reveal services that have barely been opened. Rotating subscriptions instead of maintaining every platform simultaneously can preserve access to wanted programming without paying year-round for dormant accounts. The important question is not whether each service seems inexpensive on its own, but whether the entire collection still earns its place in the monthly budget.
App and Cloud Subscriptions Hiding in the Background
A small charge from an app store can be remarkably easy to overlook. Photo editors, productivity tools, fitness applications, password managers, cloud storage and other digital services increasingly use monthly or annual subscription models. Statistics Canada’s Survey of Household Spending specifically tracks spending on software subscriptions, online storage, wellness applications and other digital services, reflecting how many separate recurring digital expenses can now sit inside a household budget.
The leak often begins with a free trial or a cheap introductory plan. Months later, the app may be rarely used while the payment continues automatically. September is a good time to open the subscription-management pages attached to Apple, Google and other digital accounts rather than relying only on memory. Cloud storage deserves particular attention because people sometimes pay for overlapping services through a phone manufacturer, email provider and workplace software package. The objective is not to cancel useful tools. It is to identify duplicates, abandoned trials and services whose annual cost no longer matches how often they are actually used.
Retail Memberships That No Longer Earn Their Keep
Warehouse clubs and online retail memberships can absolutely save money for households that use their benefits frequently. They become leaks when the annual fee survives long after shopping habits change. Statistics Canada even treats online and wholesale retail memberships—such as Costco and Amazon Prime—as a distinct household spending category, illustrating how memberships have become a normal recurring expense rather than an occasional purchase.
A useful September test is to look backward instead of forward. Rather than asking whether a membership might be useful someday, households can examine what they actually bought during the past six or twelve months and which benefits they actually used. Free shipping has little value when few orders are placed. A warehouse membership may not pay for itself when a smaller household rarely buys in bulk. There can also be overlap between memberships offering delivery, entertainment or other perks. Renewal dates deserve the same scrutiny as any other bill, particularly when automatic renewal makes doing nothing the easiest—and potentially most expensive—choice.
A Chequing Account That Still Charges Too Much
Bank fees can become almost invisible because they often arrive as the same line item every month. Yet Canadians have more lower-cost options than many account holders realize. Under Canada’s modernized Commitment on Low-Cost and No-Cost Accounts, participating institutions must offer Canadians qualifying low-cost accounts for no more than $4 a month, with at least 18 debit transactions and no required minimum balance. Certain groups qualify for no-cost versions.
That does not mean a $4 account is automatically right for every household. Someone making dozens of transactions may be better served by another package, while a person maintaining a minimum balance may receive a fee waiver elsewhere. The leak occurs when an account chosen years ago remains untouched despite major changes in income, banking habits or transaction volume. Before October, comparing the actual monthly fee, included transactions and services used can be worthwhile. FCAC provides an account comparison tool precisely for this purpose. Even a modest monthly reduction becomes meaningful when the same charge otherwise repeats twelve times every year.
ATM Withdrawals That Trigger Multiple Fees
Taking $40 from the wrong ATM can cost considerably more than the amount displayed on the withdrawal screen suggests. The Financial Consumer Agency of Canada explains that Canadian ATM withdrawals may involve several different charges: a regular account fee, a network access fee when the machine belongs to another institution, and a convenience fee imposed by a private ATM operator or another financial institution.
That makes repeated convenience withdrawals an easy money leak. The individual cost can feel too small to change behaviour, particularly during nights out, road trips or cash-only purchases. But someone making several off-network withdrawals each month is essentially paying repeatedly for access to their own money. A better September routine is to identify nearby machines belonging to the household’s financial institution, withdraw less frequently when cash is required and confirm whether the current banking package includes a certain number of withdrawals. Mobile wallets have reduced the need for cash in many situations, but when an ATM is necessary, choosing the machine matters almost as much as choosing the amount.
NSF Charges Caused by Poor Timing
A bill that arrives one day before payday can create an unnecessary banking charge even when the household has enough income overall. Canada introduced stronger protections for non-sufficient-funds fees at federally regulated banks on March 12, 2026. The new rules cap an NSF fee at $10, prevent another NSF fee from being charged on the same personal deposit account within two business days, and prevent a fee when the overdraft is less than $10.
The cap makes NSF charges less punishing than they once were, but repeated $10 hits are still wasted money. Reviewing automatic withdrawals before October can reveal payments scheduled just before income normally reaches the account. Changing a billing date, maintaining a small buffer or setting a low-balance alert can reduce the risk. The broader lesson is that cash-flow timing matters alongside total spending. A household can technically afford every monthly bill and still lose money when payment dates are poorly aligned. A few minutes spent organizing those dates can eliminate a fee that provides no lasting value whatsoever.
A Rewards Card Whose Annual Fee No Longer Makes Sense
Premium credit cards often sell themselves with travel points, airport benefits, insurance coverage or elevated cash back. Those perks can be valuable, but only when they are actually used enough to outweigh the annual fee. Canada’s Office of Consumer Affairs specifically warns that annual fees and higher interest costs on some rewards cards can cancel out the value of the rewards depending on a cardholder’s spending habits.
The calculation can change surprisingly quickly. A card chosen during a period of frequent travel may look very different after travel slows. A household that once spent heavily in bonus categories may now earn most of its rewards at a lower rate. September provides an opportunity to compare the previous year’s rewards against the next annual fee before another renewal slips through. FCAC’s Credit Card Comparison Tool allows Canadians to compare annual fees, interest rates and rewards across cards. Downgrading or switching should be considered carefully—particularly because closing older credit accounts can have other implications—but paying indefinitely for unused premium benefits is a leak worth investigating.
Credit-Card Interest on Purchases That Never Really Get Paid Off

The purchase price shown at checkout is not necessarily the final price when a credit-card balance is carried from month to month. Federally regulated credit-card issuers must provide a grace period of at least 21 days on purchases, but interest becomes a cost when balances are not paid according to the card’s terms. FCAC stresses that paying only the minimum stretches repayment and increases the total interest paid.
Its example makes the problem tangible. A $2,000 balance at 18% interest, with a $60 monthly payment, takes approximately three years and 11 months to clear and generates about $793 in interest. Raising the payment to $160 cuts the example to roughly one year and two months, with about $231 in interest. That is a large difference created without changing the original purchase. Before fall spending accelerates, reviewing balances and directing spare cash toward expensive revolving debt can stop old purchases from continuing to drain future paycheques. Even modest additional payments can reduce the duration and cost of the debt.
Buy-Now-Pay-Later Purchases That Have Started to Stack Up

Four small instalments can make a purchase seem easier to absorb than one large charge. The trouble begins when several buy-now-pay-later plans overlap. The Financial Consumer Agency of Canada warns that these arrangements can include missed-payment charges, processing fees and NSF fees, and can encourage consumers to underestimate the combined cost of multiple purchases.
Some retail credit arrangements also rely on promotional rates. FCAC gives an example in which a promotional rate could rise from 0% to 35% after a missed required payment, depending on the specific agreement. That is not a universal BNPL rate, but it illustrates why the fine print matters. September is a good month to list every outstanding instalment in one place rather than viewing each retailer separately. The important figure is the total amount scheduled to leave the account over the next several pay periods. A plan that looked harmless in isolation can become a substantial cash-flow problem when five or six similar commitments land at once.
Credit-Card Balance Insurance That Duplicates Other Protection
Balance insurance often appears as a relatively small premium attached to a credit card, which makes it easy to overlook. FCAC says credit-card balance insurance is an optional product separate from the credit card itself. Depending on the policy, it may help cover a balance after events such as disability, critical illness, hospitalization, job loss or death.
The key question is whether the coverage is needed and how it overlaps with insurance already available through an employer, personal disability policy, term-life policy or other protection. FCAC specifically advises consumers to compare balance insurance with coverage they may already have. It also says consumers can cancel credit-card balance insurance at any time, subject to the policy’s cancellation process. That makes September a practical time to scan statements for insurance premiums that have faded into the background. Cancelling blindly would be unwise because protection has value when it fills a genuine gap. Paying indefinitely for duplicated or poorly understood protection, however, can become an expensive form of financial clutter.
Mobile Data and Add-Ons That No Longer Match Actual Usage
Cellphone plans can become outdated remarkably quickly. A package chosen when someone regularly commuted, travelled or used large amounts of mobile data may be excessive after work and lifestyle patterns change. At the other extreme, a plan with too little data can trigger overage charges. The CRTC says providers generally cannot charge more than $50 in data overage fees during a billing cycle without explicit consent for additional charges.
Changing plans has also become easier in an important respect. CRTC rules that took effect June 12, 2026 prohibit certain activation and modification fees that could act as barriers to changing cellphone or Internet plans, although legitimate installation charges and expressly chosen optional products can still be charged. That makes an end-of-September telecom review especially timely. Looking at several months of actual data use is more useful than judging a plan by its advertised allowance. Canadians paying for enormous data buckets they never approach—or repeatedly buying add-ons because their base plan is too small—may both be spending more than necessary.
An Internet Promotion That Quietly Reverted to the Regular Price

Internet bills deserve another look whenever a promotional period expires. A plan can feel inexpensive for a year or two and then quietly become a much larger recurring expense once the discount disappears. Under the CRTC’s Internet Code, contracts must disclose important details including the minimum monthly charge, when time-limited discounts or promotions end, applicable equipment costs and certain cancellation information.
Those details make the original agreement useful even months after service begins. A household that signed up during a promotional campaign may discover that the price being charged today bears little resemblance to the number remembered from the advertisement. Modem or equipment rental fees can also become part of the monthly total. Before October, checking the full bill rather than only the automatic-payment amount can reveal exactly what changed. Canadians can then compare current offers or speak with their provider about a more appropriate package. The mistake is allowing inertia to turn a temporary promotional rate into years of paying the post-promotion price without reconsidering the service.
Groceries That Are Purchased but Never Eaten

Food waste may be one of the most physical money leaks in a household because the evidence eventually appears in the garbage or compost bin. Federal sources continue to identify overbuying, poor meal planning, improper storage and confusion around food-date labels as common contributors. A 2024 update cited by Agriculture and Agri-Food Canada estimated that households account for about 15% of food loss and waste across Canada’s food system.
The household cost can be substantial. The Canadian Food Inspection Agency has highlighted National Zero Waste Council research estimating avoidable food waste at roughly $1,300 annually for the average household, equivalent to about 4.5 meals a week. The exact amount will vary widely by household, but the underlying habit is easy to recognize: forgotten produce, oversized recipes and duplicate pantry purchases. September offers a natural reset as school and work routines stabilize. Planning several meals before shopping, freezing food before it spoils and checking the fridge before buying replacements can cut spending without asking anyone to eat less.
Electronics Drawing Power While Nobody Is Using Them
The television is off, the gaming console is sleeping and the charger has no phone attached, yet electricity may still be flowing. Natural Resources Canada says standby or “phantom” power can account for roughly 5% to 10% of a household’s electricity bill. Modern homes contain growing numbers of network-connected devices that remain partly active even when their main function is not being used.
No household needs to unplug everything every night. Some devices need permanent power, while disconnecting routers, security systems or necessary equipment would make little sense. The opportunity is in guest-room televisions, older electronics, game systems, printers and chargers that remain energized for convenience rather than necessity. NRCan recommends options such as unplugging rarely used devices and using advanced power bars that shut down peripheral equipment automatically. As shorter fall days begin increasing household electricity use, eliminating unnecessary standby consumption is one of the few savings measures that can continue working without requiring a recurring sacrifice once the setup is complete.
A Thermostat Schedule Left in Summer Mode
Heating is a much larger household energy expense in Canada than many smaller appliances, making thermostat settings particularly important as October approaches. Natural Resources Canada says lowering the thermostat by 1°C for an eight-hour period can reduce heating-energy consumption by about 2% in many conventional systems. It recommends programmable setback schedules where appropriate.
NRCan commonly uses 20°C when people are awake and at home and 17°C while sleeping or away as energy-saving reference settings, although individual comfort, building conditions and heating systems differ. Heat pumps and some hydronic systems require special consideration because aggressive setbacks may not work the same way. The money leak occurs when last winter’s schedule—or a temporary summer setting—no longer matches the household’s actual routine. September is the ideal time to review programmed temperatures before the heating system begins working hard. A thermostat should reflect when people are actually home, rather than heating an empty house simply because nobody revisited the schedule after routines changed.
Drafts and Dirty Filters Making the Heating System Work Harder
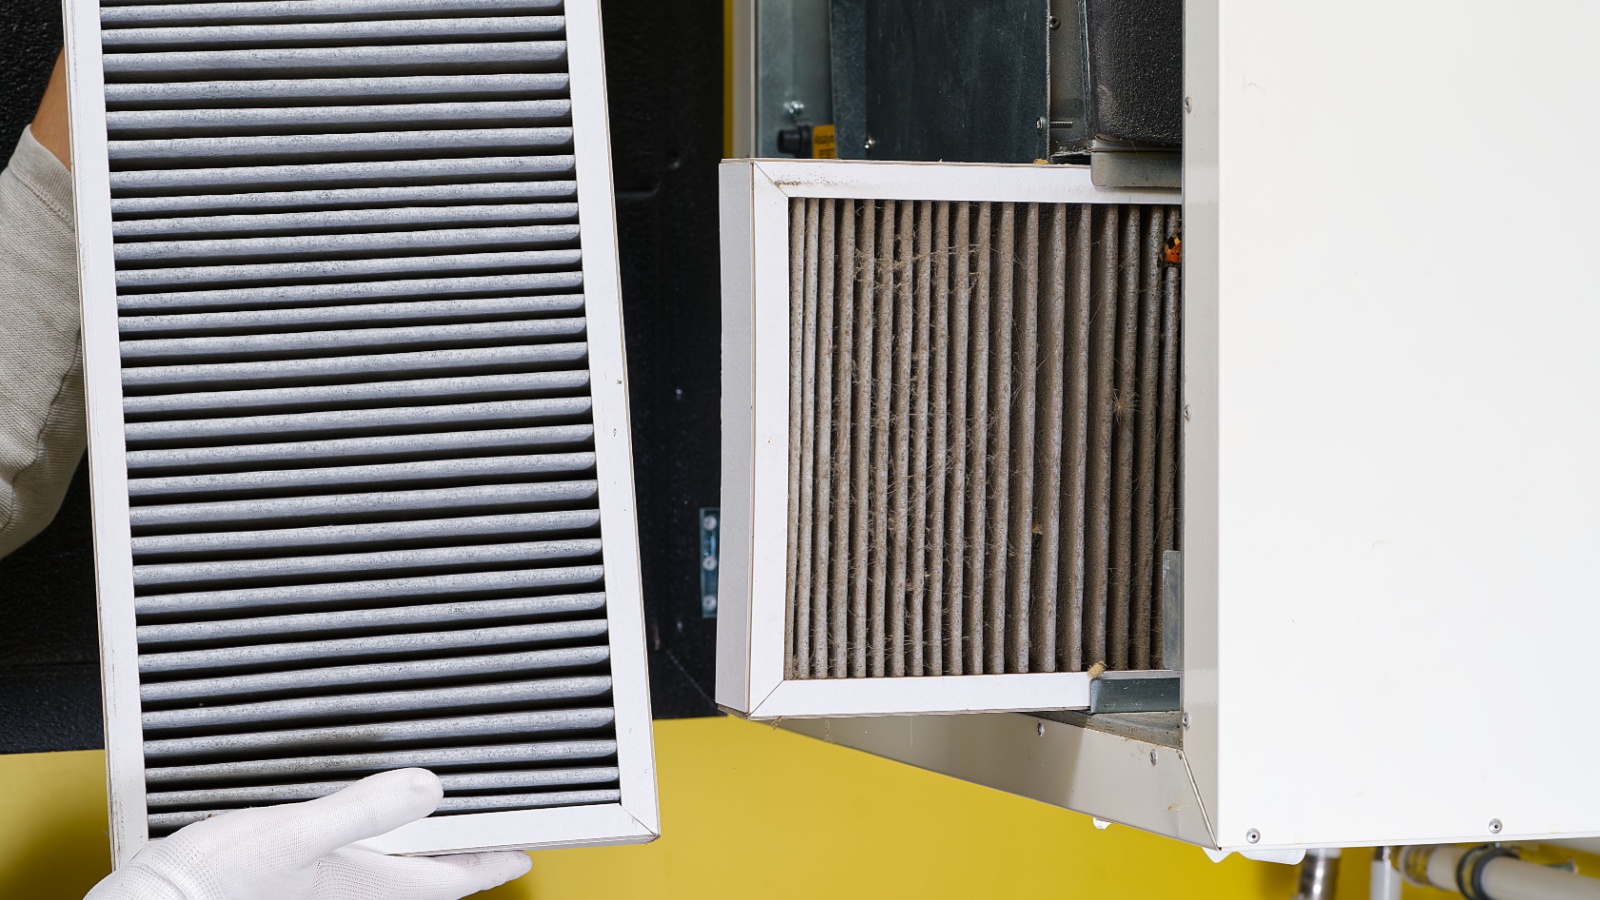
A small draft around a window can seem insignificant in September but becomes more expensive once cold weather settles in. Natural Resources Canada estimates that space heating represents about 61% of energy use in the average Canadian home. It recommends checking doors and windows for air leakage and using weather-stripping or sealant where appropriate to keep heated air inside.
HVAC maintenance is another easy area to neglect. NRCan advises following the manufacturer’s recommended maintenance schedule and notes that a clean furnace filter improves airflow. Blocked heating registers and poorly placed furniture can also interfere with warm-air circulation. None of this means every homeowner needs an expensive retrofit before October. The first fixes are often much smaller: inspect weather-stripping, check the filter, make sure registers are open and unobstructed, and identify obvious cold-air leaks. A furnace working against avoidable restrictions or a home constantly replacing escaped heat can turn a maintenance issue into a recurring utility cost throughout an entire Canadian winter.
Underinflated Tires Burning More Fuel
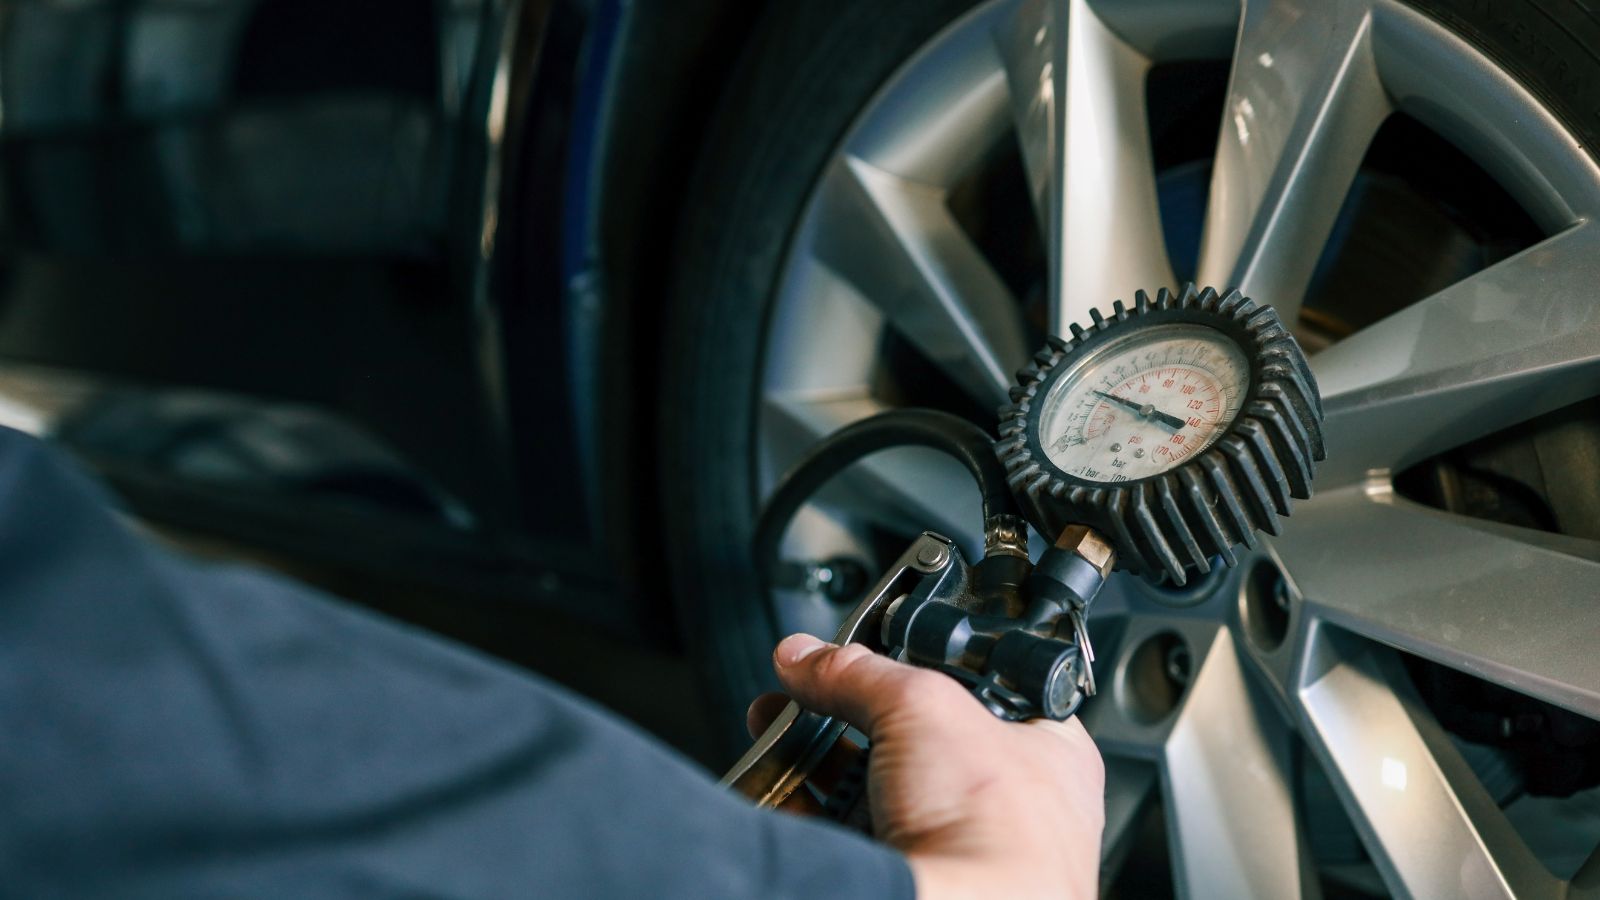
Tire pressure changes deserve more attention as temperatures begin falling. Natural Resources Canada says driving with tires underinflated by 56 kilopascals, or 8 psi, can increase fuel consumption by as much as 4%. It can also reduce tire life by more than 10,000 kilometres. Because pressure naturally changes with temperature, seasonal transitions are precisely when a tire that looked acceptable during summer may need adjustment.
The proper target is not the maximum pressure printed on the tire’s sidewall. Drivers should use the manufacturer’s recommended pressure shown on the vehicle’s tire-information placard, typically located on the driver’s door or doorpost. NRCan recommends measuring pressure at least monthly and more frequently during seasonal changes. The savings are modest on an individual tank, which is exactly why this qualifies as a money leak rather than an obvious crisis. Fuel is purchased week after week, and tires are expensive to replace. Keeping four tires properly inflated helps address both costs while also supporting predictable vehicle handling as Canadian roads head toward colder conditions.
Idling That Turns Fuel Into Nothing

A few minutes in a parking lot rarely feels expensive, which is why idling can persist unnoticed. Natural Resources Canada says an average vehicle with a three-litre engine wastes about 300 millilitres of fuel during ten minutes of idling. It recommends shutting the engine off when stopped for more than 60 seconds, except when sitting in traffic.
The habit becomes especially relevant as mornings cool down. NRCan says prolonged idling is not the most efficient way to warm a modern vehicle; driving gently warms the engine, drivetrain and passenger compartment more effectively. Its cold-weather guidance estimates that ten minutes of idling can consume roughly 0.25 to 0.50 litres depending on the vehicle and conditions. One episode is hardly catastrophic. Repeated every workday through fall and winter, however, the wasted fuel becomes meaningful. The practical fix is straightforward: avoid using the engine as a stationary heater longer than necessary and save remote-start time for situations where visibility, safety or genuinely severe conditions justify it.
Premium Gas in a Vehicle That Does Not Require It
The most expensive pump option can look like the safest choice for an engine, particularly when labels such as “premium” imply better performance. Natural Resources Canada says higher-octane gasoline does not automatically deliver higher fuel economy or more power. Unless an engine is designed to require or benefit from higher octane, buying it may be unnecessary.
That distinction matters because some vehicles require premium fuel, others recommend it for maximum performance, and many are designed to operate normally on regular gasoline. The owner’s manual and fuel-door information should settle the question. Drivers should not downgrade fuel when the manufacturer requires a particular octane rating simply to save money. The leak is paying an additional amount at every fill-up when the manufacturer does not call for it and no useful benefit is being obtained. Before October road-trip and holiday driving begins, checking the actual specification takes only a few minutes. It can eliminate a recurring expense that has sometimes continued for years simply because of habit or the assumption that a higher octane number must be better.
Auto Insurance Still Based on an Old Driving Routine
Insurance premiums are calculated using information about how a vehicle is used, so a major lifestyle change should eventually reach the insurer. Ontario’s Financial Services Regulatory Authority says kilometres driven each year and whether a vehicle is used for commuting can affect auto-insurance rates. Someone who once drove to an office five days a week but now works primarily from home may therefore have a materially different usage pattern.
Discount opportunities vary by province and insurer. British Columbia provides a concrete example: eligible ICBC customers driving under 5,000 kilometres annually may receive a 10% discount on Basic coverage, while qualifying drivers travelling under 15,000 kilometres can receive distance-based discounts on certain Optional coverage. Canadians elsewhere should ask their own insurer or broker what rules apply rather than assuming the B.C. program exists nationally. September is also a sensible time to shop around before a renewal. The objective is not to remove necessary protection, but to ensure the insurer is pricing the vehicle using current rather than outdated driving habits.
Home Insurance Renewing Without a Proper Review
Automatically renewing home, condo or tenant insurance is convenient, but the policy may contain limits, deductibles and optional endorsements selected years earlier. Insurance Bureau of Canada recommends reviewing coverage at renewal and updating a home inventory annually. It also notes that policies can contain optional protection for risks such as overland flooding, sewer backup or earthquakes, depending on the location and insurer.
The money-saving goal should not be to strip away coverage simply to produce the cheapest possible premium. A cheaper policy that leaves a major risk uninsured can be a very expensive mistake. Instead, September is an opportunity to understand what is actually being purchased. Changes in possessions, renovations, deductibles or household circumstances may make some limits inappropriate, while discounts or different deductible options may be available. An insurance representative can explain what changing those features would mean. The leak being targeted is not insurance itself; it is paying for a poorly understood policy year after year without checking whether the coverage, limits and price still fit the household.
Investment Fees That Seem Tiny Until They Compound
Investment costs rarely feel like ordinary household bills because many are deducted inside the product rather than appearing as a monthly invoice. The Canadian Investment Regulatory Organization says investors can face management fees, management expense ratios, trading expenses, brokerage commissions, account fees and other costs. These charges reduce the amount of investment return that remains with the investor over time.
The Ontario Securities Commission’s investor-education service notes that mutual-fund MERs vary considerably and are embedded in fund results. Canada is moving toward greater transparency: beginning in 2027, Total Cost Reporting will require annual reports to show additional fund-cost information, including total dollar costs and percentage costs for investment funds. Canadians do not need to wait for those statements to ask what they currently pay. September can be used to review the latest account statement, Fund Facts documents and fee schedules, or ask an advisor for a breakdown. A fee may be entirely justified by the service received, but a small percentage charged every year deserves considerably more attention than its modest-looking number suggests.
16 Costco Canada Habits That Could Be Costing Shoppers More Than They Save
The Executive Membership can feel like an obvious upgrade because the 2% annual reward sounds straightforward. For households that spend heavily at Costco Canada, the extra fee may be easy to justify. But the habit becomes costly when shoppers upgrade first and calculate later. A Gold Star Membership costs less, while Executive costs more and only pays off if eligible annual spending is high enough to offset the difference.
16 Costco Canada Habits That Could Be Costing Shoppers More Than They Save
This Options Discord Chat is The Real Deal
While the internet is scoured with trading chat rooms, many of which even charge upwards of thousands of dollars to join, this smaller options trading discord chatroom is the real deal and actually providing valuable trade setups, education, and community without the noise and spam of the larger more expensive rooms. With a incredibly low-cost monthly fee, Options Trading Club (click here to see their reviews) requires an application to join ensuring that every member is dedicated and serious about taking their trading to the next level. If you are looking for a change in your trading strategies, then click here to apply for a membership.