35,000+ smart investors are already getting financial news, market signals, and macro shifts in the economy that could impact their money next with our FREE weekly newsletter. Get ahead of what the crowd finds out too late. Click Here to Subscribe for FREE.
Donald Trump’s latest steel announcement landed at an unusually stark moment for Canada’s industrial heartland. On September 28, the U.S. president unveiled plans for a US$15-billion Mesabi Metallics steel complex in Iowa, presenting it as another sign that Washington’s tariff-heavy manufacturing strategy is drawing major investment into the United States.
Hours apart, Stelco disclosed a very different development in Ontario. The company plans to indefinitely idle cold-rolled and coated finishing operations at Hamilton Works, a decision that could affect up to 500 employees across its Hamilton and Lake Erie operations. The two announcements are not directly connected projects, but their timing captures the pressures reshaping North American steel: new capacity is being promised south of the border while established Canadian operations adjust to a market distorted by tariffs, weaker demand and changing trade flows.
Two Very Different Steel Announcements Landed on the Same Day
Trump Touts US$15B Iowa Steel Mill as Up to 500 Hamilton Steel Jobs Face Tariff-Linked Layoffs
- Two Very Different Steel Announcements Landed on the Same Day
- The Iowa Project Would Be Enormous, but Production Is Years Away
- Trump Is Putting Steel Tariffs at the Centre of the U.S. Industrial Strategy
- Stelco Is Changing Its Product Mix Rather Than Shutting Down Steel Production Entirely
- Cold-Rolled and Coated Steel Have Become a Particular Pressure Point
- Canada Has Seen How Quickly U.S. Steel Tariffs Can Change Export Behaviour
- Ottawa Has Escalated Its Response as Pressure on Canadian Producers Grows
- The Immediate Human Impact Is Being Felt in Hamilton
- The U.S. Jobs Being Celebrated and the Canadian Jobs at Risk Operate on Different Timelines
- The Same Trade Wall Is Producing Very Different Outcomes on Either Side of the Border
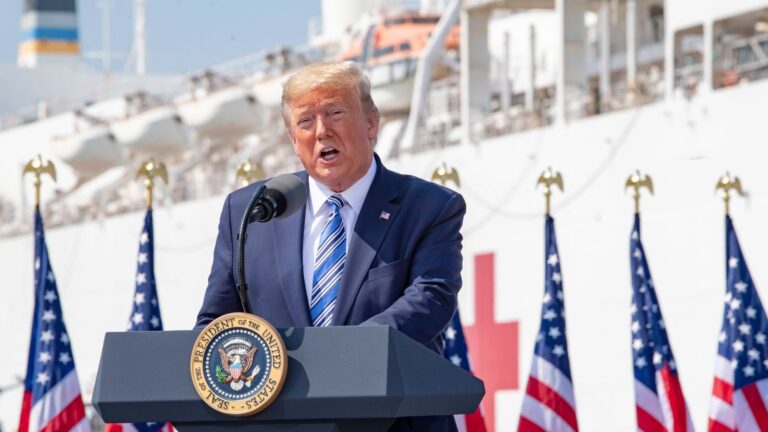
The contrast was difficult to miss. At the White House, Trump appeared with executives and Iowa political leaders to announce Mesabi Metallics’ proposed US$15-billion steel mill in southeast Iowa. The project is expected to be supplied with iron ore from Mesabi’s new mining operation in Minnesota and is being promoted as a largely domestic mine-to-mill supply chain. Trump credited his trade policies, including steep tariffs on imported steel, with encouraging companies to put manufacturing investment inside the United States rather than relying on foreign production.
In Ontario, meanwhile, Stelco said continuing market uncertainty had forced it to indefinitely idle cold-rolled and coated operations at Hamilton Works beginning around October 9. The company said as many as 500 employees could be affected across Hamilton and Lake Erie Works in Nanticoke. United Steelworkers Local 1005 has estimated that roughly 350 production workers could face layoffs. That distinction matters: the 500 figure is not necessarily 500 Hamilton layoffs, although Hamilton’s finishing operation is at the centre of the restructuring.
The Iowa Project Would Be Enormous, but Production Is Years Away
Mesabi’s proposal is substantial even by steel-industry standards. The plant is expected to begin with annual production capacity of roughly 7.5 million tons and could eventually reach around 10 million tons. The White House and Iowa officials have said the development could support approximately 5,000 to 6,000 construction jobs and at least 1,700 permanent positions. Steel production is targeted to begin as soon as 2030, meaning the permanent employment and output being discussed are projections rather than jobs or steel already entering the market.
The Iowa facility would form the downstream end of a much broader Mesabi investment. Its Minnesota mine and direct-reduction-grade pellet operation has required more than US$2.5 billion and recently began its startup phase. Federal support is also significant: the Export-Import Bank of the United States has discussed up to US$10 billion in financing connected with Mesabi’s Minnesota expansion. However, EXIM board documentation dated September 24 still described final approval as required for the Minnesota mine and pellet transaction, illustrating how parts of the broader investment remain subject to financing and implementation milestones.
Trump Is Putting Steel Tariffs at the Centre of the U.S. Industrial Strategy
Trump has repeatedly argued that tariffs are necessary to make domestic steel production more attractive. In June 2025, his administration increased Section 232 tariffs on most imported steel and aluminum from 25 per cent to 50 per cent. The White House said the measure was intended to address what it considers national-security risks from dependence on imported metals and to protect American production from excess global capacity. Additional changes announced in 2026 broadened how duties are calculated on steel, aluminum, copper and many derivative products.
During the Iowa announcement, Trump again presented those policies as a reason large industrial projects are being planned in the United States. Mesabi executives similarly emphasized a supply chain stretching from Minnesota ore to Iowa steelmaking. That argument has become central to Washington’s manufacturing policy: make imported metal considerably more expensive while improving the economics of producing within U.S. borders. Whether tariffs alone explain a particular investment is harder to establish. Companies also consider energy costs, logistics, government financing, demand, technology and access to raw materials when deciding where to commit billions of dollars.
Stelco Is Changing Its Product Mix Rather Than Shutting Down Steel Production Entirely
The Stelco announcement is significant, but it is not the closure of the entire company or even the end of all work at Hamilton Works. Stelco plans to indefinitely idle its Hamilton cold-rolled and coated finishing operations while concentrating more production at Lake Erie Works in Nanticoke. Parent company Cleveland-Cliffs has said overall steel tonnage is not expected to decline as a result. Instead, the company expects its product mix to shift toward more hot-rolled steel, with some affected Hamilton employees potentially finding positions at Lake Erie Works.
That restructuring carries additional significance because Cleveland-Cliffs only completed its acquisition of Stelco in 2024. At the time, Cliffs said Stelco’s headquarters would remain in Hamilton, that significant operations would continue in Hamilton and Nanticoke, and that at least C$60 million would be invested in the Canadian business over three years. The company also spoke of maintaining significant Canadian employment. The latest idling decision does not by itself establish whether any of those commitments have been breached, but it demonstrates how quickly the commercial environment surrounding the acquisition has changed.
Cold-Rolled and Coated Steel Have Become a Particular Pressure Point
Stelco says demand for its cold-rolled and galvanized products in the markets it traditionally serves has deteriorated sharply. By the second quarter of 2026, the company said demand for those products was nearly 25 per cent below the average quarterly level recorded in 2024. Even inside Canada, Stelco reported an approximately 10 per cent decline in market demand. Those figures help explain why Hamilton’s finishing lines, rather than overall steelmaking tonnage, became the focus of the latest restructuring.
The company links much of the pressure to the broader trade dispute. U.S. tariffs make Canadian steel considerably more expensive when it enters the American market, reducing opportunities for Canadian producers. At the same time, Canadian steelmakers have warned that barriers around the U.S. market can redirect foreign steel toward Canada, adding supply and pressure on domestic prices. Stelco has specifically cited both U.S. Section 232 tariffs and damage from steel imports into Canada while explaining the decision. The result is a difficult combination: fewer attractive export opportunities and intense competition for the Canadian demand that remains.
Canada Has Seen How Quickly U.S. Steel Tariffs Can Change Export Behaviour
There is historical evidence showing just how strongly steel trade can respond to tariffs. Statistics Canada examined the 25 per cent U.S. steel tariff and 10 per cent aluminum tariff imposed on Canadian products between June 2018 and May 2019. Researchers found that the value and volume of affected Canadian steel and aluminum exports to the United States fell by about half relative to comparable products that were not subject to those tariffs. Some exporters left the U.S. market or temporarily halted operations.
The same research found that Canadian exporters generally did not absorb the duties by sharply lowering their pre-tariff prices. Instead, U.S. importers were estimated to have paid essentially the full tariff cost through higher duty-inclusive prices. The 2018-19 episode is not identical to the current dispute—the tariff rates, products covered and economic environment differ—but it demonstrates why Canadian steelmakers treat American market access so seriously. A tariff can preserve the physical ability to export while making commercial sales much harder to justify. With current base steel tariffs reaching 50 per cent, that historical experience has become particularly relevant.
Ottawa Has Escalated Its Response as Pressure on Canadian Producers Grows
Canada has responded with its own increasingly aggressive steel protections. Effective September 8, 2026, Ottawa imposed new counter-tariffs of 15, 25 and 50 per cent on C$27.6 billion worth of U.S. products, with several steel and aluminum categories that had previously faced 25 per cent duties moving to 50 per cent. Canada has also maintained tariff-rate quotas designed to limit surges of steel from non-CUSMA countries, with above-quota imports in affected categories facing significant surtaxes.
The federal government simultaneously announced C$7.5 billion in new and enhanced assistance for Canadian workers and businesses affected by U.S. trade measures, adding to programs already introduced during the dispute. Those policies are intended both to cushion the immediate economic damage and to give Canadian producers a stronger position in their domestic market. Their existence does not guarantee that individual mills can maintain every production line. Stelco’s announcement illustrates the gap policymakers are trying to close: trade defences can restrict competing imports and provide financial support, but they cannot instantly replace lost export demand or guarantee profitable prices for every grade of steel.
The Immediate Human Impact Is Being Felt in Hamilton
Steel industry announcements are often measured in billions of dollars and millions of tons, but the Hamilton decision comes down to individual paycheques. United Steelworkers Local 1005 president Ron Wells has estimated approximately 350 production workers could be laid off, while the broader company estimate reaches as many as 500 affected employees. The union is now dealing with questions such as seniority, which workers remain on the job and whether positions at Lake Erie Works can absorb some of the employees displaced from Hamilton.
The timing adds another layer of uncertainty for families because the winding down is expected to begin in October. Hamilton has spent decades diversifying beyond heavy manufacturing, but steel remains deeply embedded in the city’s industrial identity and supply chain. A production change at a major mill can ripple into contractors, transportation providers, equipment suppliers and businesses serving steelworker households. Stelco has said a significant number of affected employees may be absorbed at Lake Erie Works, which could reduce the final number of people left without work. Until those transfers and layoff lists are settled, however, “up to 500” remains a ceiling rather than a confirmed final job-loss count.
The U.S. Jobs Being Celebrated and the Canadian Jobs at Risk Operate on Different Timelines
One of the most important distinctions in the two September 28 announcements is timing. Hamilton workers are facing changes beginning around October 9, 2026. Mesabi’s Iowa facility, by contrast, is targeting first steel production in 2030. Its thousands of construction jobs and roughly 1,750 permanent positions represent expected future employment dependent on the project advancing through construction, financing and commissioning. The Canadian job pressure is immediate; the American capacity expansion is largely prospective.
That does not make the Iowa announcement insignificant. A plant capable of producing up to 10 million tons annually could materially alter North American steel capacity if completed as proposed. But it also means the two stories should not be presented as though Iowa gained the exact jobs Hamilton lost. Mesabi and Stelco are different companies, producing different mixes of steel at different facilities. The link between them is the larger policy environment: tariffs are helping reshape where steelmakers believe they can sell profitably, where new capacity makes economic sense and which existing operations remain competitive.
The Same Trade Wall Is Producing Very Different Outcomes on Either Side of the Border
Trump’s Iowa announcement provides the clearest version of Washington’s argument for its steel policy. A foreign-owned industrial group is proposing a massive U.S. investment, using American iron ore, American steelmaking capacity and thousands of American workers. If the project reaches its planned scale, it would represent one of the biggest additions to U.S. steel capacity in decades. Trump has openly linked developments of this kind to the protection offered by 50 per cent steel tariffs.
Hamilton shows the other side of that trade wall. Canadian steel does not disappear simply because the U.S. becomes harder to access; producers have to redirect it, change products, compete harder for domestic customers or reduce operations that no longer generate acceptable returns. Stelco’s decision to idle Hamilton finishing lines while keeping overall tonnage steady is one example of that adjustment. The Iowa mill did not cause the Hamilton layoffs, and the Hamilton restructuring does not prove the Iowa strategy will succeed. Together, however, they show how dramatically tariff policy is redrawing investment and production decisions across a steel industry that spent decades building an integrated North American market.
This Options Discord Chat is The Real Deal
While the internet is scoured with trading chat rooms, many of which even charge upwards of thousands of dollars to join, this smaller options trading discord chatroom is the real deal and actually providing valuable trade setups, education, and community without the noise and spam of the larger more expensive rooms. With a incredibly low-cost monthly fee, Options Trading Club (click here to see their reviews) requires an application to join ensuring that every member is dedicated and serious about taking their trading to the next level. If you are looking for a change in your trading strategies, then click here to apply for a membership.